

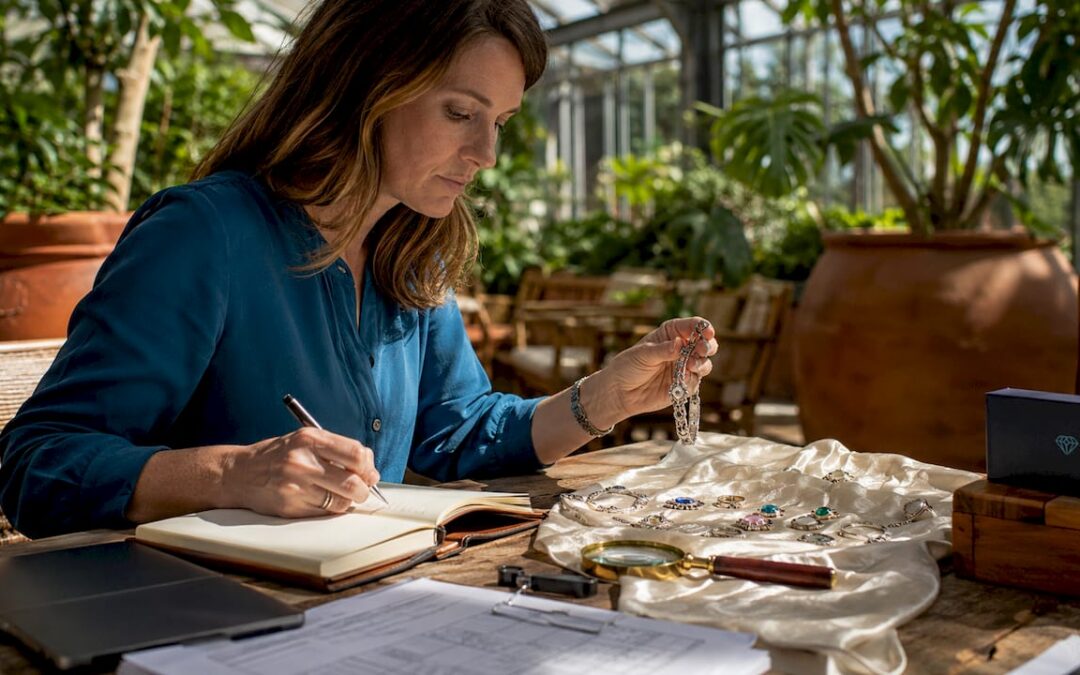
Jewelry assets in estates are classified into three primary categories: intrinsic value, design value, and historical value. Each category determines how a piece is appraised, taxed, and distributed among heirs. Understanding the types of jewelry assets in estates is the first step any executor or heir must take before probate begins. Brands like Cartier, Tiffany & Co., and Rolex sit in entirely different valuation tiers than a plain gold band, and treating them the same way creates costly legal and financial errors.
1. What are the types of jewelry assets in estates?
Jewelry asset classification in estates follows three recognized valuation categories: intrinsic value, design value, and historical or era value. Each category carries a different resale potential and requires a different appraisal approach. Executors who skip this classification step risk underreporting assets for tax purposes or dividing items unfairly among beneficiaries.
Intrinsic value covers the raw material worth of a piece. Design value reflects market demand, craftsmanship, and brand recognition. Historical value captures the premium collectors pay for pieces tied to specific eras or provenance. These are not mutually exclusive. A signed Art Deco Cartier bracelet carries all three.
2. Intrinsic value jewelry assets: what they are and how to identify them
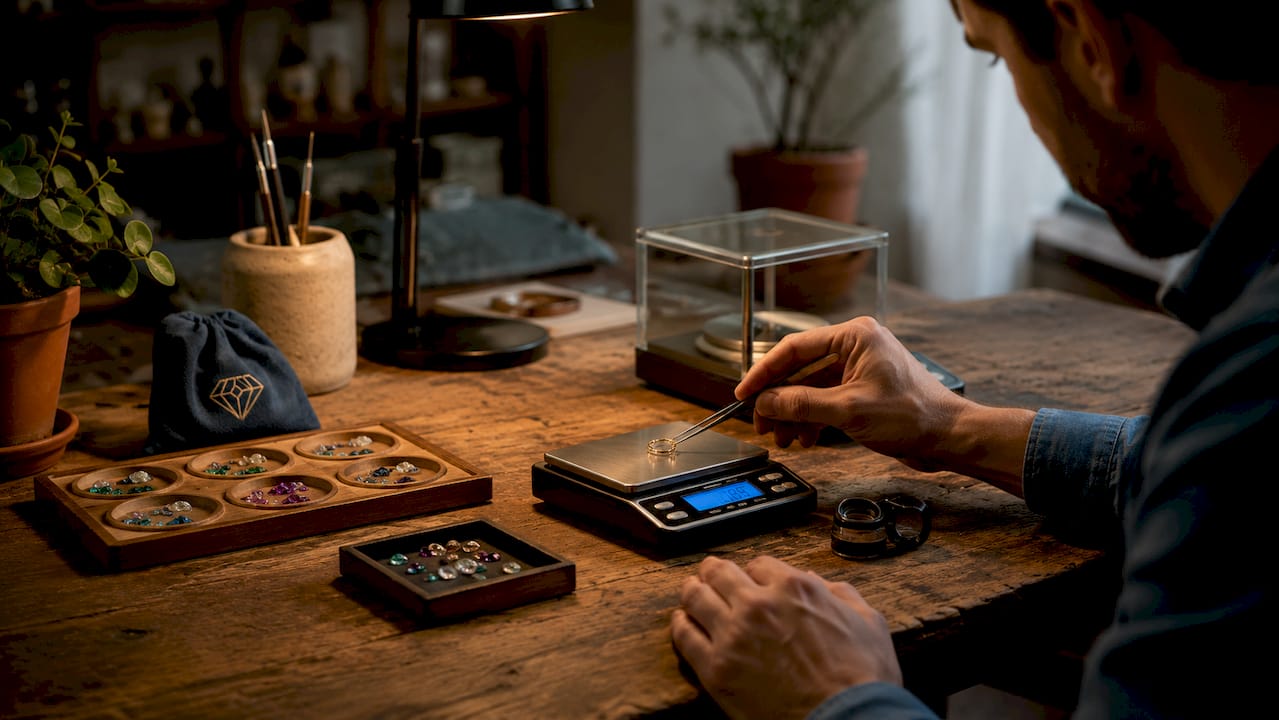
Intrinsic value is defined as the melt value of the precious metals in a piece plus the wholesale replacement cost of its stones. A broken 18-karat gold necklace with no maker’s mark is a textbook intrinsic value asset. Its worth is almost entirely tied to the weight of the gold and the quality of any diamonds or gemstones it contains.
Identifying these pieces requires reading hallmarks stamped inside rings, on clasps, or on the back of pendants. Common stamps include 750 (18k gold), 950 (platinum), and 925 (sterling silver). When hallmarks are worn or absent, XRF (X-ray fluorescence) assay testing gives a precise metal composition reading without damaging the piece.
Key characteristics of intrinsic value assets:
- No maker’s mark or brand signature
- Outdated or broken settings with no collector appeal
- Metal weight is the primary driver of value
- Stones are common grades (SI clarity, G-H color diamonds)
- Resale is typically to refiners or commodity buyers
Pro Tip: Never melt or sell intrinsic value pieces before a gemologist inspects them. Unsigned vintage pieces can hold hidden value that far exceeds melt price, and overlooking unsigned vintage jewelry is one of the most common and costly executor mistakes.
3. Design value jewelry assets: brand premium and modern wearability
Design value jewelry is defined by market demand, recognized craftsmanship, and brand identity rather than raw material content alone. A Tiffany & Co. platinum solitaire ring and a generic platinum ring of identical metal weight will sell for vastly different prices. The Tiffany name, the box, and the certificate together create a premium that can double or triple the intrinsic figure.
Luxury brand jewelry from Cartier, Tiffany & Co., and Bvlgari often appreciates across generations. That appreciation is not automatic. It depends on condition, original documentation, and whether the piece remains in current production or has been discontinued.
Luxury watches occupy their own sub-category within design value assets:
- Rolex Submariner and Daytona models hold strong secondary market premiums
- Patek Philippe complications can exceed their original retail price at auction
- Condition, service history, and original box and papers directly affect value
- Unsigned or generic watches rarely qualify as design value assets
Pro Tip: For signed pieces from Cartier or Tiffany & Co., specialist appraisal is non-negotiable. A general estate appraiser without gemological credentials will frequently undervalue these items, which exposes the executor to beneficiary disputes.
Provenance documentation matters here. Original receipts, certificates of authenticity, and service records from authorized dealers all increase the appraised value and make the piece easier to sell through reputable channels.
4. Historical and era value jewelry assets and their estate implications
Historical value jewelry is defined by its connection to a recognized design period, its rarity, and collector demand that exceeds both intrinsic and design premiums. Art Deco pieces from the 1920s and 1930s are the clearest example. Their geometric platinum settings, calibré-cut colored stones, and milgrain detailing are difficult to reproduce and command consistent premiums in the secondary market.
Art Deco and other historical eras remain stable high-value segments in 2026 secondary markets. That stability matters for estate tax reporting because it means these pieces are unlikely to depreciate before probate closes.
Other significant eras for estate jewelry include:
- Victorian (1837–1901): Mourning jewelry, seed pearl pieces, and yellow gold with enamel
- Edwardian (1901–1910): Delicate platinum and diamond lace-like settings
- Retro (1940s): Bold yellow and rose gold, large synthetic stones, wartime design influence
- Mid-Century Modern (1950s–1960s): Sculptural forms, bicolor gold, and abstract motifs
Identifying era correctly requires a trained eye. Many pieces are reproductions or later interpretations of earlier styles. An appraiser with gemological credentials and period jewelry expertise is the only reliable way to confirm authenticity and assign an era premium.
These pieces often require specialized appraisal forms that document period characteristics, hallmarks, and comparable auction results. For estates near federal estate tax thresholds, provenance documentation lowers audit risk significantly when reporting historically significant jewelry to tax authorities.
5. How executors classify and manage jewelry assets for probate and taxes
The executor’s legal duty begins the moment the estate owner passes. Executors must secure jewelry immediately upon death to avoid personal liability. Moving or distributing pieces before debts are settled can trigger legal disputes with beneficiaries and expose the executor to personal financial liability.
The classification and management process follows a clear sequence:
- Secure all jewelry in a locked location or safe deposit box before any family members take possession
- Photograph every piece from multiple angles, capturing hallmarks, signatures, and condition details
- Catalog each item noting metal type, stone descriptions, maker marks, and approximate age
- Separate by category into intrinsic, design, and historical value groups based on initial review
- Order third-party appraisals for any piece that shows a maker’s mark, brand signature, or period characteristics
- Obtain signed appraisal certificates that comply with USPAP (Uniform Standards of Professional Appraisal Practice) for legal and tax documentation
Executor documentation requirements include photographs, serial numbers, and signed appraisal certificates for full transparency. This documentation protects the executor if any beneficiary later challenges the valuation.
Pro Tip: Not every piece needs a formal appraisal. Specialized items warrant professional evaluation to protect fiduciary responsibility, but a plain silver chain with no marks can be documented by weight and current spot price.
How jewelry inventory affects estate taxes is direct. Every piece included in the gross estate must be reported at fair market value on IRS Form 706 for estates above the federal exemption threshold. Underreporting jewelry assets is an audit trigger. Overreporting inflates the taxable estate unnecessarily. Accurate classification by category is the only way to report correctly.
6. Comparing jewelry asset types: valuation and liquidation options
Understanding how each category performs at sale helps executors choose the right liquidation method. The table below summarizes the key differences.
| Asset type | Valuation basis | Liquidity speed | Best sale channel |
|---|---|---|---|
| Intrinsic value | Metal weight plus stone wholesale | Fast | Refiners, commodity buyers |
| Design value | Brand premium plus condition | Moderate | Auction houses, estate dealers |
| Historical value | Era rarity plus collector demand | Slow to moderate | Specialist auctions, private collectors |
Direct sales provide liquidity for settling debts quickly, while consignment may take months but can yield significantly more for unique high-end pieces. The right choice depends on three factors: estate urgency, asset category, and the size of the estate.
Key considerations when choosing a liquidation approach:
- Intrinsic value pieces rarely benefit from consignment. Sell them quickly to refiners at current spot prices.
- Rolex watches and signed Cartier pieces almost always perform better through specialist auction than through general estate sales.
- Historical pieces with documented provenance should never go to a general liquidator. The price gap between a specialist auction and a general sale can be substantial.
The trade-off between immediate sale and consignment is a judgment call that depends on estate urgency and the realistic ceiling for each asset. An executor managing a time-sensitive estate with outstanding debts will prioritize speed. An executor with flexibility should pursue maximum value for high-category pieces.
Key takeaways
Accurate classification of estate jewelry into intrinsic, design, and historical value categories is the single most important step for executors to fulfill their legal duties, report taxes correctly, and divide assets fairly among heirs.
| Point | Details |
|---|---|
| Three core categories | Classify every piece as intrinsic, design, or historical value before appraisal begins. |
| Secure jewelry immediately | Executors must lock down jewelry assets before any distribution to avoid legal liability. |
| Appraise signed and branded pieces | Cartier, Tiffany & Co., Rolex, and Patek Philippe items require specialist USPAP appraisals. |
| Documentation protects executors | Photographs, serial numbers, and signed certificates are required for probate and IRS Form 706. |
| Match liquidation method to asset type | Intrinsic value pieces sell fast to refiners; historical pieces perform best at specialist auctions. |
Why most executors get jewelry classification wrong
I have seen executors treat an entire jewelry collection as a single line item on an estate inventory. That approach is not just sloppy. It is a legal exposure. A Patek Philippe watch sitting in a drawer next to a bag of broken gold chains is not the same asset class, and treating them identically shortchanges beneficiaries and invites IRS scrutiny.
The most overlooked category is historical value. Executors and even some general appraisers do not recognize Art Deco or Edwardian pieces on sight. I have watched estates sell a 1920s platinum and sapphire brooch to a refiner for melt value when it was worth ten times that at a period jewelry auction. That loss is permanent and irreversible.
My practical advice: photograph everything before anyone touches it, separate branded and signed pieces immediately, and bring in a credentialed gemologist for any piece that looks older than 50 years or carries a maker’s mark. The cost of a professional appraisal is trivial compared to the cost of misclassifying a historically significant piece. Executors who skip this step are not saving the estate money. They are gambling with it.
The other mistake I see regularly is distributing jewelry to heirs before debts are settled. This creates personal liability for the executor and can unwind months of probate work. Secure first, appraise second, distribute last.
— Jake
How Stlgems supports estate jewelry appraisal and sales
Handling estate jewelry correctly requires more than a general appraiser. Stlgems provides concierge gemologist services built specifically for estate situations, from USPAP-compliant appraisals to hands-on guidance for executors navigating probate requirements.
Whether you need to classify a collection of unsigned vintage pieces, get a certified appraisal for a signed Cartier bracelet, or explore estate jewelry sales options that maximize value for beneficiaries, Stlgems delivers transparent, credentialed support at every step. Every appraisal comes with full documentation that satisfies IRS Form 706 requirements and protects executors from beneficiary disputes. Contact Stlgems to schedule an evaluation before probate closes.
FAQ
What are the three types of jewelry assets in estates?
Estate jewelry is classified as intrinsic value (metal and stone melt worth), design value (brand and craftsmanship premium), and historical value (era rarity and collector demand). Each type requires a different appraisal method and liquidation strategy.
How does jewelry inventory affect estate taxes?
Every jewelry piece in the gross estate must be reported at fair market value on IRS Form 706 for taxable estates. Accurate classification by category is the only way to report correctly and avoid audit triggers from the IRS.
Do executors need a professional appraisal for all jewelry?
Not every piece requires a formal appraisal. Plain metal items can be documented by weight and spot price, but signed pieces from brands like Cartier or Tiffany & Co. and any watches from Rolex or Patek Philippe require specialist USPAP-compliant appraisals to protect fiduciary duty.
How should executors divide jewelry assets among heirs?
Executors should complete full appraisals and classification before any distribution. Dividing jewelry by category value rather than piece count prevents disputes and ensures each heir receives a fair share of the total estate value.
When should an executor use consignment versus direct sale for estate jewelry?
Direct sale works best for intrinsic value pieces where speed matters and price is commodity-driven. Consignment through a specialist auction house is the better choice for design value and historical value pieces where collector demand can push prices well above a quick-sale offer.